Duqu Raises €1.5M To Unlock Cash Trapped In Unpaid Invoices Within Hours
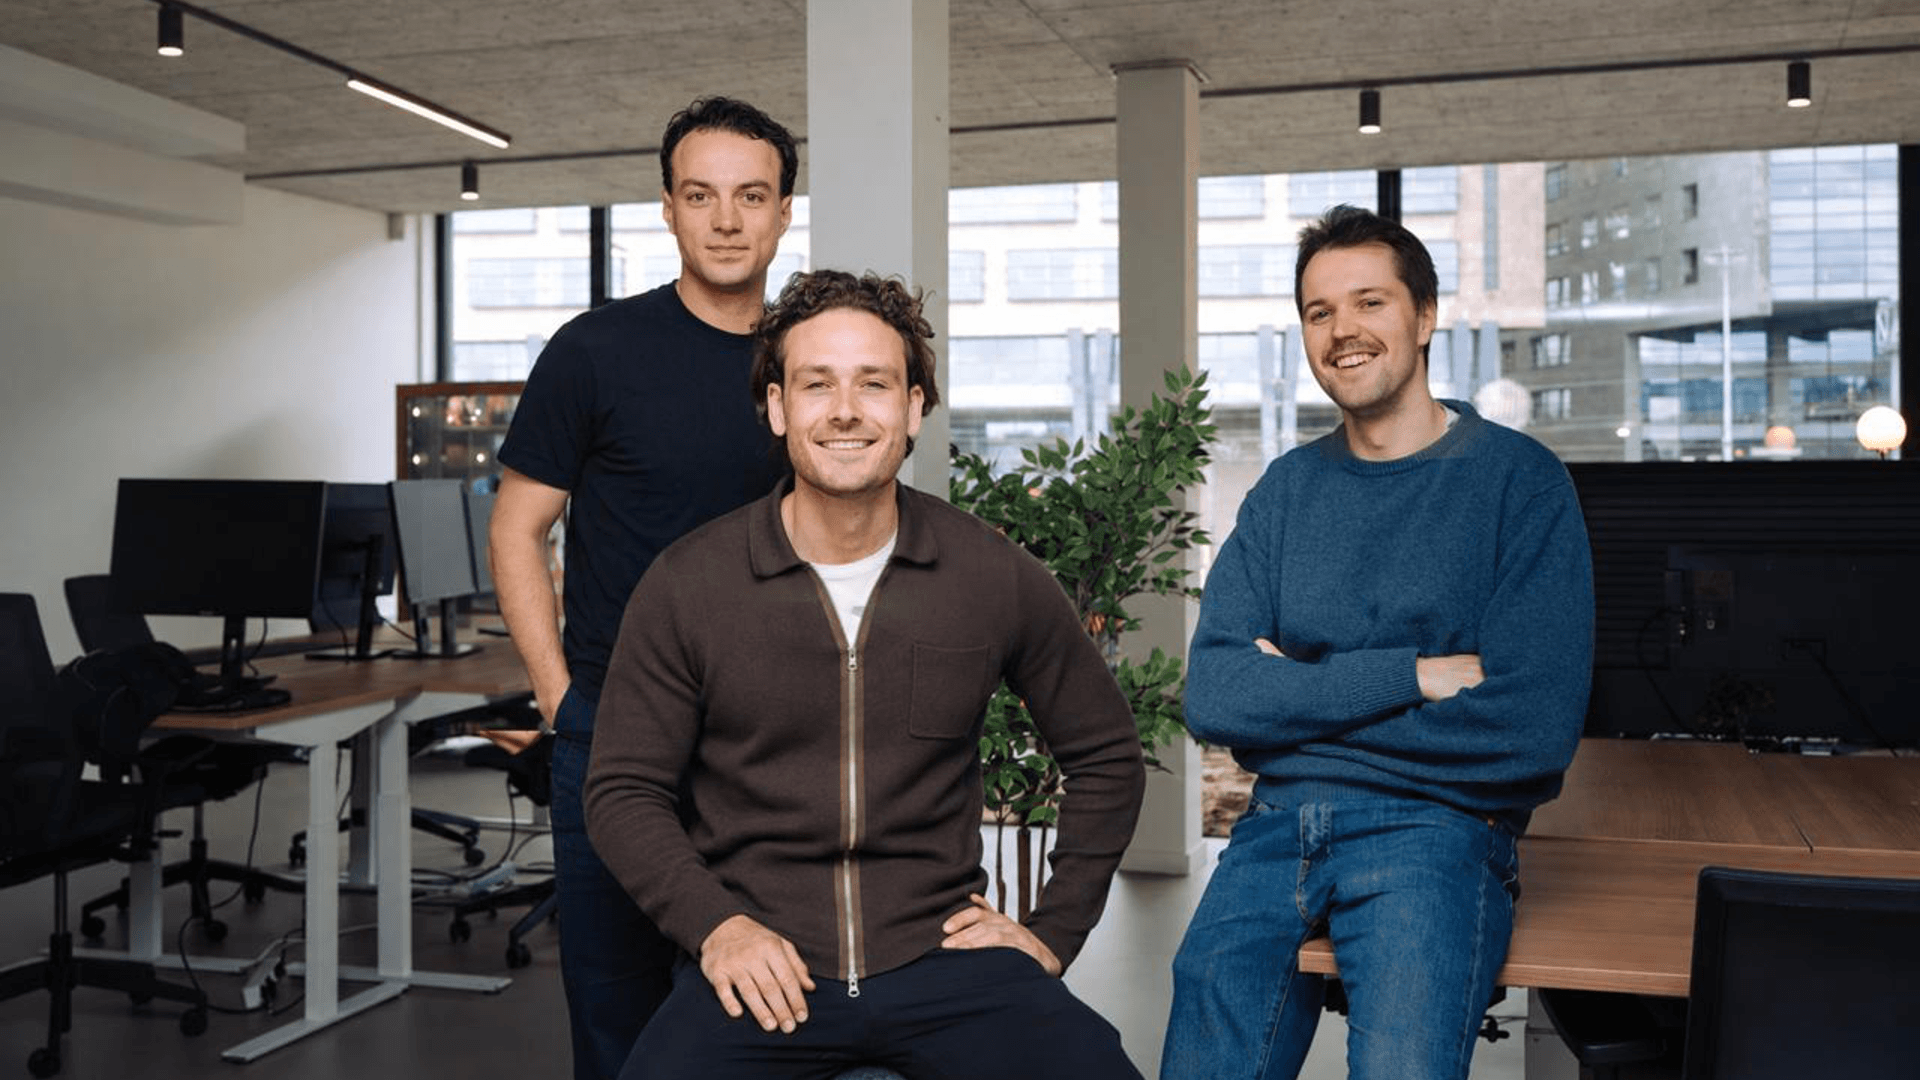
Maas de Goede, Thijn van Helvoirt, Victor Brouwer, and Diederik Nassenstein
Image credit: Duqu
Duqu, an Amsterdam based fintech company, has raised 1.5 million euros in pre‑seed funding to expand a platform that gives businesses same‑day access to cash tied up in unpaid B2B invoices, addressing a late payment problem the company says leaves nearly half of Dutch invoices settled after their due date.
The round was backed by Curiosity VC and No Such Ventures. Duqu was founded by Maas de Goede and Thijn van Helvoirt and operates a dual business model, running its own direct invoice advance platform for businesses while separately developing white‑label AI underwriting technology that banks, lenders and leasing companies can license to power their own working capital products.
The problem Duqu is built around is a straightforward but persistent one across B2B commerce. According to the company, businesses in the Netherlands pay 46 percent of their B2B invoices after the agreed due date, leaving suppliers waiting for money they have already earned while still needing to cover ongoing costs such as payroll, inventory, marketing and hiring. Duqu has framed the underlying frustration in fairly direct terms, pointing out that businesses today can arrange almost anything else instantly, yet after completing work for a client they can still wait weeks to actually receive payment for it, a mismatch between how quickly business gets done and how slowly it gets paid for that the company argues has become increasingly out of step with how everything else in commerce now operates.
Duqu's core product addresses that gap by giving businesses access to money they have already earned but are still waiting to receive, providing short‑term advances against outstanding invoices rather than requiring a business to simply wait out its customers' payment terms. The company has structured that offering specifically to avoid the drawbacks associated with traditional invoice factoring, a longer‑established form of invoice‑based financing that typically requires a business to sell its invoices outright and often hands the factoring company direct control over collecting payment from the business's own customers. Under Duqu's model, businesses retain full ownership of their invoices and control of their customer relationships throughout, with Duqu functioning purely as a source of short‑term liquidity rather than taking over the underlying commercial relationship.
Speed is central to how Duqu differentiates its product from more traditional working capital financing. Once an advance request is approved, funds are transferred within 24 hours and, according to the company, often within a single hour, a turnaround considerably faster than the days or weeks that conventional bank‑based working capital facilities can require. Pricing is structured around actual usage rather than a standing facility, with no minimum or maximum advance amount and no fee charged unless a business actually draws on an advance, an approach intended to let businesses use the product flexibly for occasional cash‑flow gaps rather than committing to a fixed credit line whether they need it in a given month or not.
Underpinning that speed is the AI underwriting engine the company has developed alongside its direct‑to‑business product. That underwriting technology is designed to assess funding applications and price risk automatically, removing much of the manual review and back‑and‑forth documentation that has traditionally slowed down invoice‑based financing decisions at conventional lenders. Duqu is positioning that underwriting technology as a separate, licensable product in its own right, aimed at banks, alternative lenders and leasing companies that want to offer faster, AI‑driven working capital products of their own without building comparable underwriting infrastructure from scratch.
The new funding will go toward growing both halves of Duqu's business in parallel, its own working capital platform serving businesses directly, and the white‑label AI underwriting technology it is building for other financial institutions to license. That dual approach gives Duqu two distinct paths to scale, expanding its direct customer base of businesses seeking faster access to cash, while also building a second revenue stream from licensing its underlying risk assessment technology to larger, more established lenders who may prefer to buy proven underwriting infrastructure rather than build their own.
Duqu enters a European invoice financing and working capital market that already includes a range of established and newer players pursuing related strategies, from larger trade finance platforms such as Dublin's Teybridge Capital Europe, which recently secured a funding line to expand its own working capital solutions across multiple regions, to earlier‑stage entrants like Brussels‑based Husk, which raised pre‑seed funding to build cashflow optimisation tools specifically for early‑stage businesses. What differentiates Duqu within that field is its combination of a fast, usage‑based direct product for businesses with a separate AI underwriting engine built to be licensed outward, a structure that gives the company exposure to both the growing direct demand for flexible working capital and the broader appetite among traditional lenders to modernise their own underwriting processes without building that capability in‑house. Whether that dual strategy proves more durable than focusing on a single business line will likely become clearer as Duqu works to prove its underwriting model at greater scale, both through its own advances and through the lenders it hopes will eventually license the technology behind them.
Topics
Stay informed
Startup news in your inbox
Get important funding rounds, founder stories, and startup updates.
No spam - only important startup updates.